15.1 Commercial banks
No special category for commercial banks
Under VoTa, a commercial bank is simply a private business. The Non-Discrimination Principle (NDP) does not permit the State to create a special legal category for banks or to treat people differently because they provide banking services. Banks are governed by the same universal laws as every other person and business, including the provisions implementing the Non-Aggression Principle (NAP) and the ordinary rules governing property, fraud, contracts, and breaches of contract.
Consequently, the State cannot impose capital or reserve requirements specifically on banks, insure their deposits, provide emergency liquidity or a lender-of-last-resort facility, rescue them when they fail, or manipulate interest rates through a conventional central bank. Nor can it license banking as a privileged occupation or restrict entry into the market. Anyone may offer banking services to the public on any terms to which the parties voluntarily agree, subject only to the same universal laws that apply to everyone else.
Financial intermediaries
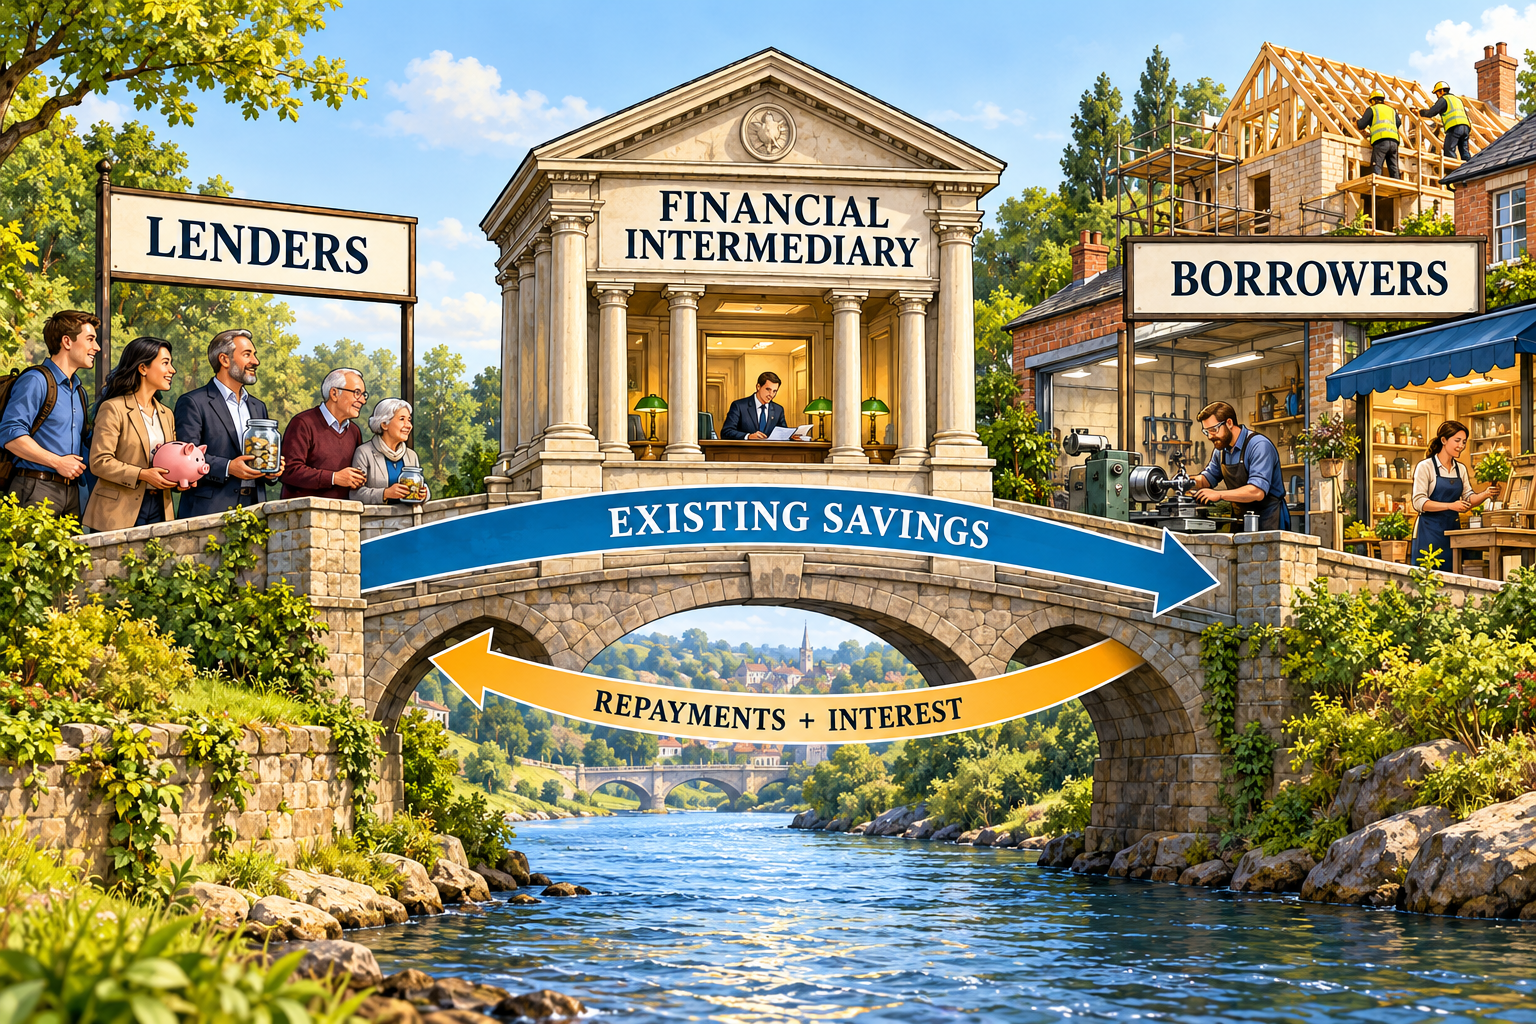
Central Bank currency exists only as balances in accounts at the Central Bank. Lending or borrowing that currency therefore necessarily involves transferring it between Central Bank accounts. A commercial bank may maintain records which it calls bank accounts on its own computer systems, but those records do not hold Central Bank currency. They record private claims against the commercial bank.
A commercial bank dealing in Central Bank currency can only transfer currency that already exists. It may act as an intermediary by connecting people who make existing currency available with people who wish to borrow it. It may assess borrowers, arrange loans, pool funds, manage repayments, and bear or distribute credit risk according to its contracts. When it makes a loan of Central Bank currency, existing currency is transferred to the borrower's Central Bank account. The commercial bank cannot issue Central Bank currency or increase its total quantity when it extends credit. What the borrower must provide in repayment is determined by the loan contract and need not be Central Bank currency.
This form of intermediation may involve what is commonly called fractional-reserve banking. The term applies when an intermediary's private claims are redeemable in Central Bank currency but it keeps less Central Bank currency immediately available than the total face value of those claims. In this context, a reserve is simply Central Bank currency held against the intermediary's private redemption promises, not a separate settlement asset. A person who lends Central Bank currency to an intermediary normally expects interest in return for accepting the risk that the intermediary will invest the currency and may suffer losses. The arrangement is not fraud when that use and risk are disclosed, but the intermediary commits fraud if it represents itself as merely holding the currency in custody while using it for investment. Lenders are largely responsible for deciding which intermediaries they trust. Anyone unwilling to accept that risk can simply retain Central Bank currency in an account at the Central Bank. Because Central Bank currency is not diluted by monetary inflation, leaving it there does not expose the holder to a continuing loss of purchasing power caused by expansion of its supply.
Competition
Anyone can lend money under any terms they choose. Market competition is unfettered. Interest rates are set by competition and reflect the risk perceived by lenders, based on collateral and the likelihood of default.
Interest rates are price signals which help investors compare opportunities and make sound decisions about how capital should be used. When those signals reflect the actual supply of funds, demand for credit, and risk of loss, they help investors avoid malinvestment. It is therefore important that interest rates are determined by the market rather than manipulated by a central bank.
Commerce services
Commercial banks and other private businesses may provide commerce services such as point-of-sale devices and payment applications. When a consumer makes a purchase, these services must produce a transfer of Central Bank currency between Central Bank accounts, as required by the constitution. They do not operate a separate settlement system or substitute their own liabilities for the currency used in commerce.
The Central Bank implements much of the underlying payment process because it must implement tax choice. Point-of-sale systems are service layers built on top of that infrastructure. The Central Bank exposes a standard interface through which competing providers can initiate the required transfers and supply devices, software, merchant services, and other conveniences.
This open and standardised interface permits fierce competition among banks and other private providers. They may also compete with publicly provided commerce services, funded through tax choice, which could include point-of-sale devices. Competition should make these systems cheap and robust, while the presence of many interchangeable providers makes it unlikely that the failure of any single entity would cause a major disruption to commerce.
Money custodian services
A bank or other private business may offer to hold Central Bank currency in custody for a customer. Under such a contract, the customer retains ownership of the currency and the custodian is required to keep it continuously available for transfer on demand. The custodian may safeguard the currency and transfer it according to the customer's instructions, but may not lend, pledge, invest, or otherwise use it for its own benefit.
This is 100% reserve banking: the full amount of Central Bank currency held in custody must remain available on demand. If a custodian promises to retain the currency on demand but secretly uses it or does not hold the required reserve, it has misrepresented the service and dealt with the customer's property without authority. That is fraud as well as a breach of contract. This corresponds to Murray Rothbard's argument that lending currency represented as a demand deposit is fraudulent when the representation means that the currency remains the customer's property and is available in full on demand (see Anatomy of a Bank Run).
Under VoTa, there is little reason to purchase this service. The Central Bank already holds Central Bank currency for account holders free of charge and provides robust, convenient access to it. A private custodian would duplicate that service while adding its own operating and fraud risks, and would ordinarily need to charge a fee. Specialist uses may include escrow, trusts, estate administration, and other arrangements in which an independent custodian releases currency only when agreed conditions are satisfied. Their value lies in conditional or fiduciary control rather than ordinary safekeeping. Outside such cases, money custodian services are likely to be extremely rare.
Runs remain possible on redeemable private bank liabilities
A private bank claim is not Central Bank currency. If its contract promises redemption in Central Bank currency, simultaneous redemption requests may exceed the amount the bank has immediately available. This is a run on those redeemable private liabilities. Direct access to safe Central Bank accounts does not entitle claim holders to better terms than the contracts they accepted.
The outcome depends on those contracts. Maturity dates, notice periods, queues, liquidity suspensions, proportional reductions, collateral rights, creditor priorities, or insolvency procedures may apply. If the bank fails to perform an unconditional promise, it is in breach and may be insolvent. If it applies a clearly disclosed contingency exactly as agreed, the delay or loss is part of the risk accepted by the customer rather than a failure of Central Bank currency.
Losses fall on the bank, its owners, investors, and contractual creditors according to their agreed priority. A run may destroy the market value of private claims and cause the bank to fail, but it cannot destroy Central Bank currency, reduce balances owned by unrelated account holders, or interrupt commerce conducted through the Central Bank Payment System.
Ambiguous arrangements are interpreted as contracts
If it is unclear whether an arrangement is custody or credit, the dispute is resolved under the ordinary law of contracts. A court determines the meaning a reasonable party would have understood from the agreement, account description, payment of interest or custody fees, advertising, customary usage, transaction records, and other representations. Material redemption conditions cannot be hidden and invented only after customers request payment. Calling an account a deposit does not override clear terms showing that it is a loan or private investment claim.